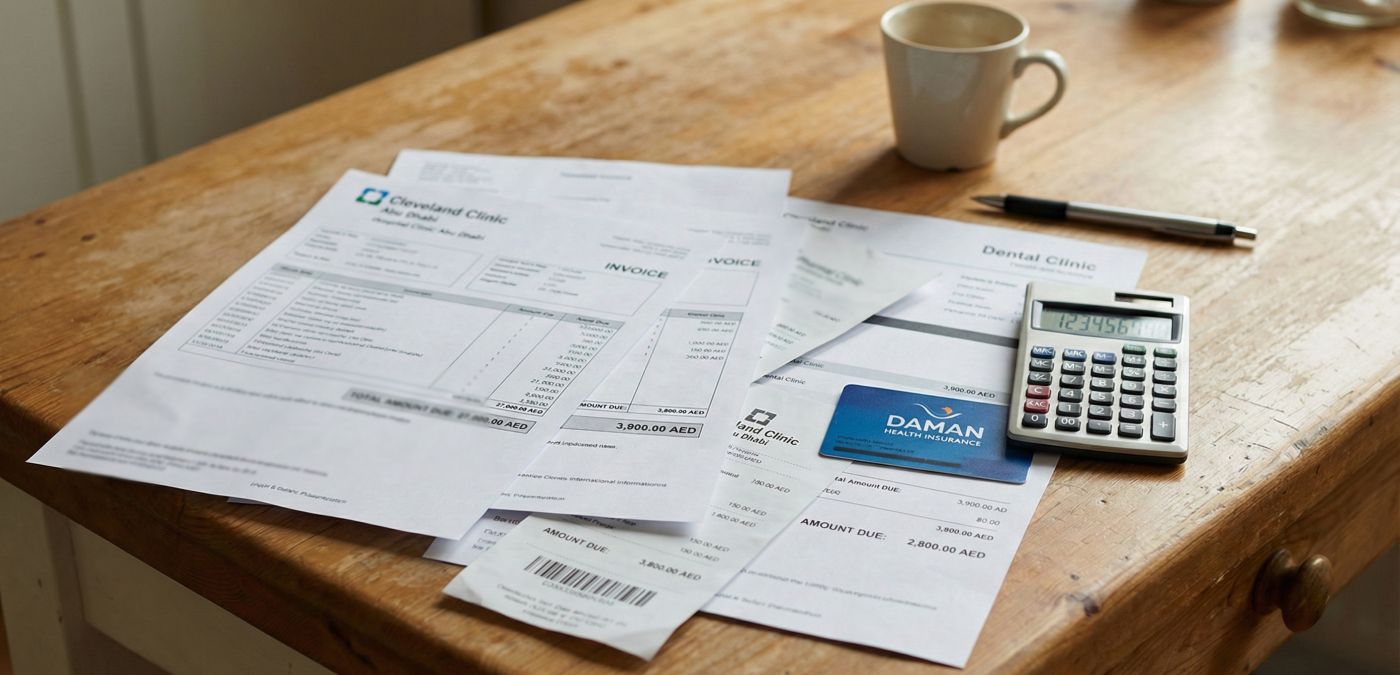
I moved here in January 2022 for a product management job. Tech salary, "comprehensive benefits," Dubai Marina apartment—looked perfect on paper. Three years later, I've probably spent close to AED 40,000 on healthcare mistakes I didn't see coming, and I'm still figuring some of this out.
This isn't a guide. I don't have it all figured out. But here's what's cost me money and stress.
The Insurance Card Looked So Simple
My company gave me a Daman insurance card during onboarding. Green card, my photo, policy number. HR said "show this at any hospital." I put it in my wallet and didn't think about it again for four months.
Then I tore my ACL playing football in Al Quoz. Pain was immediate, couldn't walk. Friends drove me to American Hospital because it was close and looked expensive (which I thought meant good).
The ER doctor was great. Examined my knee, ordered an MRI, said I'd need surgery. Handed me a quote: AED 62,000 for the surgery plus three nights inpatient.
I gave them my insurance card, feeling smug that I wouldn't pay anything.
The billing person came back twenty minutes later: "Your insurance approves AED 35,000. You pay the difference."
I stared at her. "What difference? I have insurance."
She showed me the approval letter. My plan covered the surgery, but American Hospital wasn't in my network. My insurance paid "out of network rates," which were 60% of what the hospital actually charged. I owed AED 27,000.
Plus there was a AED 500 deductible.
Plus I owed 20% co-insurance on the approved amount: another AED 7,000.
Total bill to me: AED 34,500.
I didn't have AED 34,500. I'd moved here three months ago. I put AED 20,000 on a credit card and borrowed AED 15,000 from my brother.
What I didn't know:
- "Network" vs "non-network" matters more than I thought
- Most employer insurance has co-insurance (you pay a percentage)
- Deductibles reset annually
- Some hospitals are 3x more expensive than others for the same surgery
- I should have called my insurance company first
What I still don't fully understand:
- How to check if a hospital is in-network before an emergency
- Whether my network is good or bad compared to other plans
- If I can upgrade my insurance mid-year (HR says no, but I've heard other people can?)
Three months later, I got a bill for another AED 3,800 from the anesthesiologist. Apparently he wasn't in network either, even though the hospital was. I'm still paying that one off in installments.
The Day I Learned What "Pre-Authorization" Means
Six months in, I was still having knee pain. My GP referred me to an orthopedic specialist for a follow-up MRI. He was at Mediclinic City Hospital. The doctor scheduled the MRI for the following week.
I showed up, got the scan, went home. Two weeks later I got a letter: "Claim denied - no pre-authorization."
I called my insurance company confused. "What's pre-authorization?"
"You need to call us before certain procedures and get approval."
"How was I supposed to know that?"
"It's in your policy document."
I'd never read my policy document. It was 47 pages and sent as a PDF during onboarding when I was trying to find an apartment and set up my bank account.
The MRI cost AED 2,800. I paid it.
I now know you need pre-auth for:
- Any imaging that costs more than AED 1,000 (MRI, CT scans, some ultrasounds)
- All surgeries, even minor ones
- Endoscopies
- Physical therapy after the first few sessions
- Sometimes specialist visits at certain hospitals (this one still confuses me)
What I still don't know:
- Exactly which procedures need pre-auth for MY specific plan
- How long pre-auth takes (I've heard 24-72 hours but does it vary?)
- What happens if you need something urgently but can't wait for pre-auth
- If I can retroactively get pre-auth if the doctor forgot to mention it
My current strategy: I call my insurance company before any medical appointment that isn't a basic GP checkup and ask "do I need pre-authorization for this?" They've started recognizing my voice.
Nobody Told Me About The Prescription Thing
I take two maintenance medications: one for blood pressure (I'm 34 but it's genetic), one for ADHD. In Toronto, my insurance covered both. I'd get 90-day supplies, pay a small co-pay, done.
Dubai was different.
First issue: My insurance has a AED 1,500 annual cap on prescriptions. My medications cost about AED 4,800 per year total. So I pay AED 3,300 out of pocket annually.
But that's not even the expensive part.
My ADHD medication (Concerta) is a controlled substance in the UAE. I learned this when I tried to fill my Canadian prescription at a pharmacy in Dubai Mall. They looked at me like I'd asked for cocaine.
"You need a UAE prescription from a licensed psychiatrist."
I found a psychiatrist. Waited three weeks for an appointment. The visit cost AED 850. She evaluated me (even though I had ten years of Canadian medical records), then wrote a prescription - but only for 30 days. She said I'd need to come back every month for a new prescription because of UAE controlled substance laws.
Monthly psychiatrist visits: AED 600 each (I found a cheaper doctor after the first few months, now it's AED 380-450 depending on if it's a quick refill or we actually talk).
So my annual ADHD medication costs:
- Medication: AED 3,600 (AED 300/month)
- Psychiatrist visits: AED 4,800-5,400 (AED 400-450 x 12 months)
- Total: AED 8,400-9,000
Plus the blood pressure medication isn't covered after I hit my AED 1,500 cap, so that's another AED 1,200.
I'm spending AED 10,000+ per year on medications that cost me AED 600 per year in Canada.
Things I've learned:
- Controlled substances require paper prescriptions, stamped, maximum 30-day supply
- Most employers don't cover prescriptions well (or at all)
- Importing any controlled medication requires MoHAP pre-approval or customs will seize it
- Hospital pharmacies charge 2-3x more than retail pharmacies for the same medication
- Generic versions are usually 40-60% cheaper if you ask
Things I'm still figuring out:
- Whether I can get my psychiatrist to write longer prescriptions (some people say you can get 2-3 months at once but my doctor says no?)
- If there are cheaper psychiatrists who can do quick refill appointments
- Whether I can use telemedicine for prescription renewals (I've heard mixed things)
- How to fight with my insurance to increase the prescription cap
My brother keeps telling me to just bring a supply from Canada when I visit, but I'm pretty sure that's illegal and I don't want to risk it.
The Emergency Room Bill That Made No Sense
Last July, my son (he's 6) had a severe allergic reaction to something - we still don't know what. His face swelled up, he was wheezing. I called 998 immediately.
Dubai Ambulance came in maybe 8 minutes. Paramedics were great. They took him to Rashid Hospital (government hospital) ER.
They treated him, gave him epinephrine and antihistamines, kept him for observation for 3 hours. He was fine. We went home that night.
Three weeks later I got the bills:
- Ambulance: AED 3,200 (not covered by insurance)
- ER visit: AED 1,800 (partially covered)
- Medications: AED 600 (not covered)
I paid AED 4,600 total.
Here's what confuses me: my insurance says it covers emergency services. But apparently there are rules about which ER you go to and what "emergency" means. The insurance rep on the phone told me that in true emergencies, they're required by DHA to cover stabilization, but then there are rules about network hospitals and balance billing after you're stabilized.
I still don't fully understand how this works. I asked the rep: "So should I have called you before calling 998?" and she said "No, in life-threatening emergencies call 998 first." But then how am I supposed to control where the ambulance takes me?
What I think I know now:
- 998 ambulance usually goes to Rashid Hospital (government, cheaper)
- Ambulance costs vary, AED 2,000-4,000+ depending on what equipment they use
- Insurance has to cover stabilization in real emergencies but can limit coverage after that
- Some people say you should tell the ambulance which hospital you want but I don't know if they listen
What I definitely don't know:
- Should I have my insurance company's emergency number saved and call them en route to the hospital?
- Does insurance cover ambulance transport or not? (I got conflicting answers)
- If I'd gone to a private hospital ER would it have been more or less expensive?
- What counts as "real emergency" vs. "urgent but not emergency"?
I asked my HR person and she didn't know either. She said most people just go to urgent care clinics instead of ERs when possible, which... okay but what if you can't tell how serious it is?
I now have the numbers for three urgent care clinics saved in my phone, but I don't know how to decide in the moment whether something is "urgent care" or "ER" level.
The Dental Disaster
I've always had okay teeth. Regular cleanings, one cavity in my twenties, nothing major.
Eight months into Dubai, I bit down on something hard and part of my molar cracked. Not painful immediately, but I knew I needed to see a dentist.
My health insurance: doesn't cover dental at all. I'd assumed it was included. It wasn't.
I went to a clinic in Marina. They took X-rays, said I needed a crown. Quoted me AED 3,500 for the crown plus AED 400 for the X-rays and consultation.
I nearly fell out of the chair. In Canada, my insurance covered 80% and the crown would've been CAD 800-1,000. This was 4x more.
The dentist was nice about it. Said "This is Dubai dental pricing. We're like US private dental rates."
I asked if there were cheaper options. He said I could try clinics in Karama or Bur Dubai that cater to lower-income expats, or I could fly home and get it done there.
I couldn't take time off to fly to Canada for a crown. I got the crown in Dubai. AED 3,900 total after they found another issue while working on the first tooth.
My wife needed a filling two months later: AED 1,200. My son needed sealants on his molars: AED 800.
First year dental: AED 5,900.
I immediately bought dental insurance for the second year. Cost: AED 1,800/year for family coverage. It covers:
- 100% preventive (cleanings, checkups)
- 80% basic procedures (fillings)
- 50% major procedures (crowns, root canals)
- Annual limit: AED 5,000
Example plans I looked at (verify current terms):
- Daman Dental: ~AED 850/year, AED 3,000 annual limit
- Nextcare Dental: ~AED 1,200/year, AED 5,000 annual limit
- Neuron Dental Plan: ~AED 950/year, AED 3,500 annual limit
(Note: These shift frequently - check current coverage, waiting periods, and networks)
The insurance isn't perfect (50% of a crown is still expensive), but it's better than paying full price.
What I wish I'd known:
- Dental is separate from health insurance and usually not included by employers
- Dubai dental costs are comparable to US private rates
- Some cheaper options exist in Karama/Deira but quality varies
- Dental insurance usually has 3-6 month waiting periods for major work
- Flying to India/Thailand for major dental work is apparently a thing people do
What I still don't know:
- If the quality at cheaper dental clinics is actually worse or if it's just location-based pricing
- How to evaluate dentists here (no Yelp, no real review system)
- Whether my current dental insurance is good or if I'm overpaying
I'm Still Figuring Out "In-Network"
I mentioned the ACL surgery was out-of-network. Three years later, I still find the network thing confusing.
My insurance card has a helpline number. I've learned to call them before any non-emergency medical thing. The conversation usually goes:
Me: "I need to see a dermatologist for this rash. Where should I go?" Them: "You can go to any dermatologist in our network." Me: "Okay, which ones are in network?" Them: "I can give you names of clinics." [They list 6-8 clinic names, none of which mean anything to me] Me: "Which one is closest to Dubai Marina?" Them: "I don't have location information. You'd need to google them."
So then I google the clinics, figure out which one is closest, call to book an appointment, and they say "We don't accept Daman insurance" even though the insurance company just told me they're in-network.
This has happened four times.
I think what's happening is: the insurance company's list is outdated, or there are different types of Daman plans and some clinics only accept certain tiers, or the clinic staff are wrong. I don't know.
What sort of works:
- Calling 2-3 clinics directly and asking "Do you accept Daman insurance, policy type [whatever my policy type is]?" before booking
- Going to larger hospital systems (Mediclinic, Aster) because they usually accept most insurance plans
- Asking coworkers where they go
What doesn't work:
- Trusting the insurance company's provider list
- Assuming a place accepts my insurance just because they accept "Daman" generally
- Assuming anywhere expensive automatically accepts all insurance
I still occasionally end up somewhere out-of-network and don't realize until I'm checking out and they hand me a bill instead of just swiping my insurance card.
Random Expensive Things I Didn't Expect
Vaccinations for my son: Not covered by insurance unless it's on the UAE mandatory schedule. His school required additional vaccines. AED 1,200.
Prescription sunglasses: Needed prescription sunglasses for driving. Insurance covers basic eye exams but not glasses. AED 1,800.
Mental health: Started seeing a therapist after a stressful project at work. Insurance covers maximum AED 5,000 per year for mental health. Sessions are AED 600 each. Hit my cap after 8 sessions. Still seeing the therapist but paying out of pocket now.
Sports injuries: I play football (soccer) every weekend. I've had three sports injuries requiring treatment. My insurance covers it, but I've learned the clinic near the sports fields charges 50% more than other clinics for the same treatment. I now drive 20 minutes to a cheaper clinic.
Vitamin D test: Everyone in Dubai is apparently Vitamin D deficient even though we have sun 360 days a year (because we're all inside in air conditioning). Doctor recommended I get tested. Test cost AED 150, not covered. I was deficient. Now I take supplements (AED 30/month).
What I Think I've Learned (But Not 100% Sure)
About insurance:
- The card is just the start. Read your policy document or at least skim it
- Call the insurance helpline before anything expensive or non-routine
- "Comprehensive coverage" doesn't mean everything is covered
- Pre-authorization is a thing you need to remember
- Many plans cap prescriptions, dental, mental health, or exclude them entirely
- Networks matter but are confusing and possibly not always accurate
About costs:
- Hospital ERs are expensive, urgent care clinics are cheaper
- Hospital pharmacies charge 2-3x retail pharmacies
- Different hospitals charge wildly different amounts for the same procedure
- Ask for generic medications
- Dental and glasses are usually not covered
- Flying home for major procedures might actually be cheaper sometimes
About the system:
- It's not like Canada/UK/Australia public health systems
- It's not like US insurance (even though it looks similar)
- You're expected to be an active consumer - shop around, ask prices upfront, negotiate sometimes
- Many doctors don't know what your insurance covers - you have to check yourself
- Mistakes are expensive and there's not much recourse
What I'm still working on:
- Building an emergency fund for unexpected medical costs
- Figuring out if I can upgrade my insurance to something better
- Understanding what procedures I can delay until I visit home vs. need to do here
- Finding a better psychiatrist situation for my ADHD meds
- Actually keeping track of medical expenses for tax purposes (someone told me you can claim this but I haven't figured out how)
Things That Have Helped
Insurance card photo: I keep a photo of my insurance card (front and back) on my phone. Easier than carrying the physical card everywhere.
Saved numbers in phone:
- Insurance helpline
- 998 (emergency)
- 901 (police non-emergency)
- 997 (fire/civil defence)
- Dubai Poison & Drug Information Center: 800-424
- DHA helpline: 800 342
- Three urgent care clinics near where I live/work
- My GP's direct line
- Pharmacy delivery services
Google sheet: I track all medical expenses now. Helps me see patterns (like realizing I was overpaying at one pharmacy) and gives me data when arguing with insurance or budgeting for next year.
Coworkers: Asking coworkers about their doctors, which pharmacies they use, where they go for different things. The informal network is honestly more useful than the official insurance provider list.
Employer wellness screening: My company offers a free annual health screening. I ignored it for two years. Now I do it every year and catch small problems before they become expensive problems. Vitamin D deficiency, borderline high cholesterol, blood pressure creeping up—all caught during free screening.
What I'd Tell Someone New
You're going to make mistakes. You're going to overpay for something. You're going to end up at the wrong facility or miss a pre-authorization or not realize something isn't covered.
Budget for it. Keep AED 10,000-20,000 accessible for unexpected medical costs, especially in your first year.
Call your insurance company. A lot. Before appointments, before procedures, when you get confusing bills. The helpline number is on your card - use it.
Ask coworkers and friends for recommendations. "Which doctor do you see? Which pharmacy? Where do you go for X?" Dubai expat networks are how information actually flows.
Read your insurance policy document. I know it's boring and long. At least skim it for: what's covered, what's not, what needs pre-authorization, annual limits, network lists.
Don't assume anything works like it did in your home country. Even if you're from the US and have insurance experience, Dubai is different. Even though they use the same terminology (deductible, co-insurance, pre-authorization, network), the way it works is different.
Keep receipts and records. You'll need them when disputing charges, filing claims, or trying to figure out why you're paying so much.
And honestly? I'm three years in and still learning. Last month I discovered that my insurance covers physiotherapy but only at specific clinics, and the clinic I'd been going to for six months wasn't one of them. I'd paid AED 3,600 out of pocket that could have been covered if I'd gone to a different clinic.
This stuff is complicated. Everyone here is figuring it out as they go.
Last updated: October 2024. Insurance policies, prices, and regulations change frequently. Everything here is based on my experience with my specific insurance plan (Daman EBP tier). Your insurance will be different. Verify everything with your insurance provider.
Also: I'm not a healthcare expert or insurance specialist. I'm just a guy who's made expensive mistakes and is trying to help others avoid them. If you're making important medical decisions, talk to actual professionals, not random people on the internet.